First up, let’s be clear about what international health insurance in Thailand really means.
It isn’t travel insurance. If that’s what you’re looking for, you’ll need a different type of policy altogether.
International health insurance is comprehensive medical cover designed for expats. It typically provides:
- High coverage limits (often millions in USD)
- Access to private hospitals in Thailand and worldwide
- The ability to be treated outside Thailand (e.g. return to home country or regional hubs like Singapore)
- More flexible long-term protection that follows you across borders
By contrast, local Thai health insurance is designed primarily for treatment inside Thailand. It usually offers:
- Lower overall coverage limits
- Strong networks of Thai private hospitals
- Lower premiums
- More restrictions around international treatment or overseas cover
In simple terms:
International insurance = global flexibility + higher protection
Local insurance = Thailand-based care + lower cost
Neither is “better” in absolute terms — they serve different needs. The right choice depends on your lifestyle, travel habits, health status, and budget.
If you already know you want global cover and want to see real pricing, use the link below.
→ Get a quote here (takes 2 minutes)
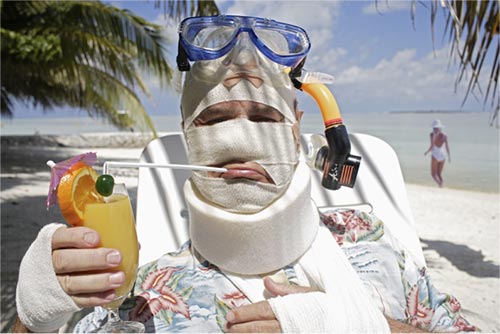
Don't end up like this dude!
Why This Choice Matters More Than You Think
One of the biggest mistakes expats make is choosing insurance based purely on price or convenience, without understanding how fundamentally different these systems are.
International policies are built around freedom of movement and continuity of care.
Local Thai policies are built around affordable access to treatment within Thailand’s private hospital system.
This difference affects everything from where you can be treated, to how claims are handled, to what happens if you leave Thailand for extended periods.
If you’re planning to stay long-term, travel regularly, or want the option of treatment back home, international cover often becomes the more stable long-term choice.
If you’re settled in Thailand, rarely travel, and want lower monthly costs, local insurance can be perfectly adequate.
10 Things to Consider Before Choosing Health Insurance in Thailand
1. Company Reputation
When choosing international health insurance, reputation should come first.
You want a provider that is financially stable, transparent, and known for fair claims handling.
Key things to look at:
- Customer reviews and expat feedback
- Financial strength ratings
- Claims history and reputation for speed
- Global hospital network quality
Good insurers don’t just sell policies — they support you when things go wrong.
2. Customer Service
Medical issues are stressful enough without chasing an insurer.
Look for:
- 24/7 global support
- Fast response times
- English-speaking advisors
- Ability for family members to communicate on your behalf if needed
Quick reality check (before we go deeper)
At this point, it’s worth seeing what your actual cost looks like — because people often overestimate international premiums.
3. Lifestyle & Habits
Your premiums are directly influenced by:
- Smoking
- Alcohol consumption
- Fitness levels
- BMI
- Risky hobbies (diving, motorsports, etc.)
Even small lifestyle differences can significantly affect cost.
4. Pre-Existing Conditions
This is one of the most important factors.
You need to understand:
- What is considered “pre-existing”
- Whether it is excluded or covered with limits
- Waiting periods
- Underwriting requirements
Always disclose fully as omissions can invalidate claims.
5. Claims Process
A good policy is defined by how it behaves at claim time, not purchase time.
Look for:
- Direct billing with hospitals
- Clear claims timelines
- Simple documentation requirements
- 24/7 claims support
6. Inpatient vs Outpatient Cover
Many people underestimate outpatient costs.
Outpatient includes:
- Specialist visits
- Scans
- Minor procedures
- Follow-ups
In Thailand, these can add up quickly, especially in private hospitals.
7. Home Country Cover
Ask yourself:
- Do I travel back regularly?
- Do I need treatment flexibility outside Thailand?
Some international policies allow extended home-country treatment periods — local policies usually do not.
8. Dental & Vision
Often overlooked, but expensive over time.
Check:
- Routine dental cover
- Major procedures (crowns, implants)
- Optical cover (glasses, contact lenses)
9. Evacuation & Repatriation
Essential for serious emergencies.
Covers:
- Medical evacuation to another country
- Transport during natural disasters or unrest
- Repatriation of remains
This is one of the key differentiators between basic and premium cover.
10. Maternity Cover
Maternity is rarely included in basic plans.
Check:
- Waiting periods (often 10–24 months)
- Coverage limits
- Hospital and delivery options
- Pre/post-natal care inclusion
If you’re planning a family, this becomes a major decision factor.
Local Insurance Option (Often Overlooked but Very Relevant)
While international insurance gets most of the attention, many expats in Thailand choose local health insurance as a cost-effective alternative.
Local plans often provide:
- Lower monthly premiums
- Strong coverage in Thai private hospitals
- Faster approval for routine care
- Simpler claim structures
If you want to compare local Thai insurance options from multiple providers in one place, you can get quotes on Mr Prakan:
→ Compare local Thailand insurance quotes here
This is often the quickest way to see whether a local plan could realistically meet your needs before committing to international cover.
Frequently Asked Questions About Health Insurance in Thailand
1. What is the difference between international and local health insurance in Thailand?
International health insurance is designed for expats who want global medical coverage, higher limits, and the ability to be treated outside Thailand if needed. Local health insurance is focused on treatment inside Thailand only, usually in private hospitals, and comes with lower premiums but more limited cover.
2. Do I really need international health insurance in Thailand?
It depends on your lifestyle. If you rarely leave Thailand and are happy using Thai private hospitals, a local policy may be enough. If you travel regularly, want access to treatment in other countries, or prefer higher coverage limits, international insurance is usually the better fit.
3. Is local Thai health insurance good enough for expats?
For many expats, yes. Thailand has excellent private hospitals, and local insurance can provide solid coverage at a lower cost. The main limitation is that it generally won’t follow you outside Thailand or offer the same level of flexibility as international plans.
4. Why is international health insurance more expensive?
International policies cost more because they cover you across multiple countries, offer higher claim limits, and often include benefits like medical evacuation, repatriation, and treatment in top-tier hospitals worldwide.
5. Can I use international health insurance in Thailand?
Yes. Most international health insurance plans include full coverage in Thailand, often with direct billing at major private hospitals in Bangkok, Chiang Mai, Phuket, and other major cities.
6. What is usually excluded from health insurance in Thailand?
Exclusions vary by provider, but common ones include pre-existing conditions (unless agreed otherwise), cosmetic procedures, and sometimes dental or maternity care unless added as optional extras.
7. How does pre-existing medical conditions affect insurance?
Pre-existing conditions may be excluded, covered at a higher premium, or subject to waiting periods depending on the insurer. Full disclosure is essential, as failure to declare medical history can invalidate a policy.
8. Is outpatient care important in Thailand?
Yes, often more than people expect. Outpatient care includes consultations, scans, and minor treatments, which can add up quickly in private hospitals. Many expats choose to include outpatient cover even if they are otherwise healthy.
9. What does evacuation and repatriation cover?
This covers emergency transport to another hospital or country if local treatment isn’t sufficient, as well as returning you home in serious medical situations or after death. It’s one of the most important parts of any international policy.
10. How do I choose between international and local insurance?
Think about how often you travel, whether you want global medical access, your budget, and your long-term plans. If you’re settled in Thailand, local insurance can be efficient. If you want flexibility and higher protection, international insurance is usually better.
Last Updated on

Lana Scott says
Seems to me that communication to and from the Insurance Co. is key if you're living in Thailand. What happens if, for any reason, you are hospitalized and unable to communicate?? I'm sure that this is fairly common. Generally speaking, are hospitals equipped to deal with this for you?
Jun 19, 2022 at 12:53 am
TheThailandLife says
Jun 19, 2022 at 4:20 am
Nutnarin says
Jun 15, 2020 at 1:51 am
TheThailandLife says
Jun 15, 2020 at 5:27 am
Bubba says
Add to that, with China's bans on tour group travel due to the Wuhan virus, the Thai government will be surprised at the size of the deficit that they will be facing for 2020. The government is already talking about shut-downs due to deficits..
Jan 26, 2020 at 10:44 pm
John H says
Jan 26, 2020 at 8:02 am
Andreas Whittell-Rudeberg says
Jan 24, 2020 at 1:39 pm
James E says
Jan 25, 2020 at 6:56 am
TheThailandLife says
Jan 25, 2020 at 6:24 pm
Bubba says
Mar 14, 2020 at 7:58 am
TheThailandLife says
Mar 14, 2020 at 10:24 pm
Peter says
Feb 21, 2020 at 4:08 pm
Kim Finegan says
Dec 14, 2019 at 3:15 pm
napa burgisser says
Sep 30, 2019 at 2:36 pm
Troup Dresser says
Jun 16, 2019 at 3:56 pm
TheThailandLife says
Jun 17, 2019 at 4:00 am
James E says
Jun 17, 2019 at 8:43 am
kelvin says
A non O visa is the one you get in Thailand
Each year you renew your Visa and so check in your passport what type you have
Dont worry!!!
Jun 17, 2019 at 11:27 am
philip Robinson says
Nov 10, 2019 at 4:54 pm
James E says
Nov 11, 2019 at 1:00 am
Noel says
Mar 14, 2020 at 1:31 am
Kelvin Bamfield says
The other Visa is the X visa and this is for the investment of 3 million baht
So far these are the only Visa's that will require health care insurance -
No need to speculate until there are changes as in Thailand there is always Plan B
May 20, 2019 at 9:33 am
Kelvin Bamfield says
Also, I understand that somewhere in all this there will be a provision for "well healed" retirees that have a few million in the bank and agree that they will not be a burden on the Thai hospital system.
The system does need a serious overhaul and maybe a "means" test should be applied. ie. You own a condo or 2 and so no rent, one produces income?, pension income, interest earned in the bank = calculated to see what you need to stump up each year for an "extension of stay" then the applicable insurance policy attached (good luck with that one as pre-existing and age are a huge factor)
Also, the hospitals were all asked to forward their costs for procedures and medical drugs, etc. to the Government. Many did not and now are taking action to stop or protract the need to report. All in all, this may not eventuate in July and may be amended and there are too many Rumsfeld known unknowns.
TIT- just wait
May 18, 2019 at 10:34 am